Brent at $117 Already Tops the World Bank Crisis Forecast
The World Bank's October outlook puts 2026 Brent at $91 and a 2027 crisis case at $105. December futures just printed $117.38, so the worst-case commodity shock is already in the tape.
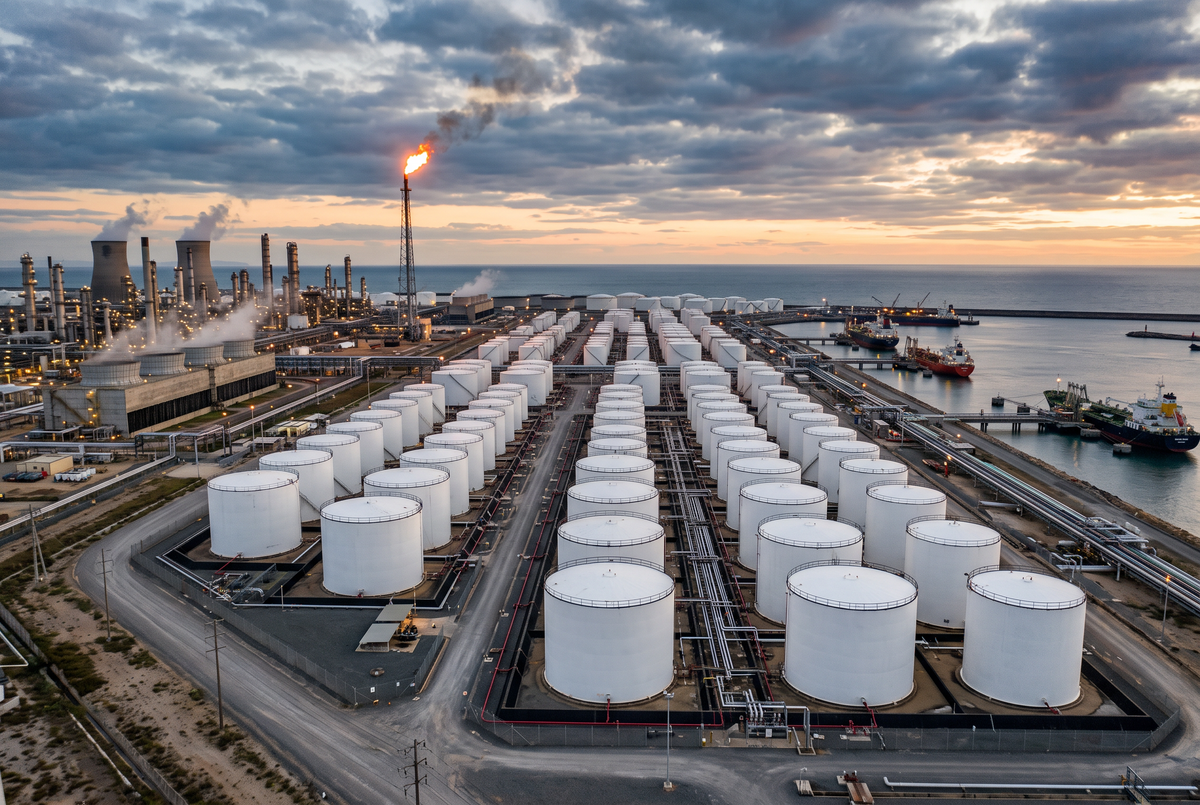
The World Bank's October Commodity Markets Outlook already looks behind the tape. In a late-October release, the Bank said Brent would average $91 a barrel in 2026, up from $69 in 2025, and ease to $79 in 2027. Its adverse case, if the risks stacked, put 2027 Brent at $105.
Two sessions later, December Brent futures advanced $2.50, or 2.2%, to $117.38 a barrel. West Texas Intermediate climbed $2.04, or 2.2%, to $104.09. Oil was on track for a fourth straight monthly gain, with Brent up about 13% for the month and WTI about 15%.
The Bank's forecasts assume no major intensification of conflicts affecting global commodity supplies. Front-month crude is trading as if that assumption has already failed, which is why the inflation, food, and rates read-through is arriving now rather than in 2027.
A synchronized jump, not a single oil spike
The World Bank is not describing a one-market squeeze. Commodity prices as a group are set to rise 23% in 2026, then decline 7% in 2027. Energy is the largest piece, projected to rise 32% this year after three years of declines, before moderating in 2027. Metals prices are set to reach a new high, rising 25%, with aluminum, copper, and tin all hitting record highs. Precious metals are forecast to increase 40% in 2026. Food commodity prices are expected to rise about 10% in 2026 and another 7% in 2027, a cumulative increase of 18%. Fertilizer prices are set to rise 14% in 2026.
That mix hits households, manufacturers, and farmers at once. Higher crude feeds into diesel and freight. Higher fertilizer raises the cost of the next harvest. Higher industrial metals raise the cost of wiring and capital goods. The Outlook's special focus finds that links between commodity-price volatility become more pronounced during periods of stress, including since the start of the Middle East conflict. Industrial metals transmit the most volatility on average, though oil's role rose markedly after the conflict began.
Ayhan Kose, the World Bank's Deputy Chief Economist, put the policy problem in one line: "Commodity markets are being hit by several major shocks at once. Higher energy costs and trade disruptions are driving up prices across a broad range of commodities, threatening to worsen inflation, food insecurity, and economic growth."
Oil supply is falling faster than demand
The energy forecast is not a demand boom. Global oil supply is projected to fall 5.2% in 2026, the largest drop in more than four decades outside the 2020 global recession. Oil consumption is expected to decline 2.5%, the third-largest annual contraction on record, after 2020 and 1980. Supply is shrinking by more than demand, which is how you get a 32% energy-price jump even as the world uses less crude.
The tape is adding a risk premium on top of that arithmetic. A tanker in the Strait of Hormuz was hit by explosive devices attached by a small boat, according to the United Kingdom Maritime Trade Operations, on the same session that pushed December Brent through $117. The Bank's adverse scenario already contemplated those risks stacking: Brent averaging $105 a barrel in 2027, and food commodity prices 12% higher than the baseline. Front-month prices have already cleared the oil half of that case.
That does not make the 2027 average a settled fact. Futures can reverse, and the Bank still sees prices declining 7% next year in its baseline, with Brent easing to $79. The market is no longer waiting for the adverse case to show up in an annual average. It is paying it now.
Food, inflation, and the end of easy easing
Food is the slower fuse. An 18% cumulative rise in food commodity prices through 2027, plus 14% fertilizer inflation in 2026, is a household shock before it is a market story. The Bank's adverse case adds another 12% to food prices versus baseline if the shocks combine. That is the food-insecurity channel Kose flagged.
For central banks that were starting to ease, the sequence is awkward. Energy up 32%, metals at records, precious metals up 40%, and food still climbing into 2027 is a recipe for stickier headline inflation. A rate-cut path built on fading goods prices does not survive a synchronized commodity shock.
The World Bank Group has made $50 billion to $60 billion available through existing instruments, including $25 billion in pre-arranged financing. That is a development-finance backstop, not a substitute for cheaper oil. The damage still lands in import bills, fertilizer access, and fiscal room in commodity-importing states.
The analytical mistake would be to treat $91 as the working forecast and $105 as a tail. December Brent at $117.38 has already overtaken both. The Outlook's own condition, no major intensification of conflicts affecting supply, is the assumption the market has stopped granting. Until that condition is restored, the World Bank's worst-case commodity map is the one being priced, and the inflation and food-security costs travel with it.